

This article is adapted from AQ’s special report on Mexico’s path forward
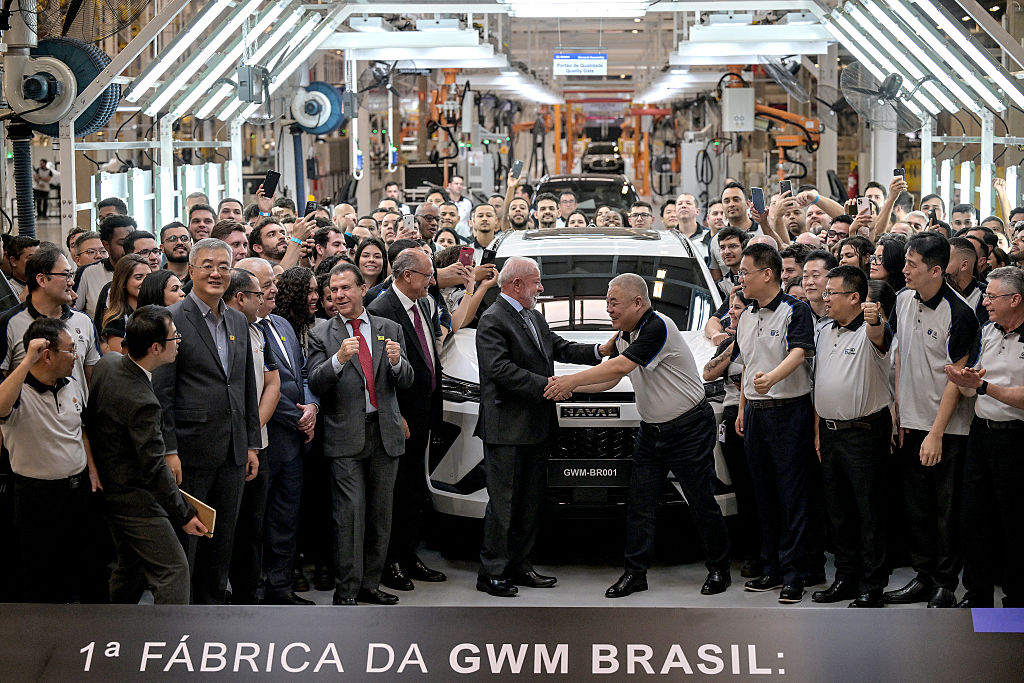
Despite all the upheaval of President Donald Trump’s “Donroe Doctrine,” the main drivers of the China-Latin America relationship remain largely intact. A year ago, I wrote in a cover story for Americas Quarterly that Beijing was mostly focused on acquiring the region’s commodities and exporting to its markets.
That dynamic still holds, and trade between China and the region has continued to rise, up 3% between 2024 and 2025. This is partly due to the choices of the U.S., which has embraced trade policies that have pushed some of its partners toward other markets.
I also noted that China had reworked parts of its playbook for Latin America (and much of the rest of the world). In recent years, it has traded large-scale loans and mega-projects for smaller deals more directly supportive of its own industrial and export-related interests.
This is part of Beijing’s effort to zero in on narrower strategic priorities. In 2023, about 60% of Chinese FDI in Latin America was concentrated in what China calls “New Infrastructure” industries: those it has identified as critical drivers of future growth. They are generally industries experiencing rapid, tech-driven innovation, including telecommunications, fintech, and energy.
These trends appear to be deepening. China now has less capacity for overseas lending and investment, so it’s being more selective. The country’s 15th Five-Year Plan (2026-2030), issued in March, prioritizes export growth and support for national champions in key sectors.
This is reflected in China’s greenfield investment (GI) in Latin America. Though it spiked by almost 400% last year, that was due to a single project: a $39 billion ByteDance-backed data center in Brazil. Setting aside that outlier, the data shows China’s GI on a clear downward trend. It has also become more concentrated. Even after discounting the ByteDance data center, about 30% of the dollar value of all its 2024 and 2025 GI in the region went to two sectors: advanced manufacturing and information and communications technology.
Key shifts
Geopolitical competition is intensifying, and for Latin America, trade-offs are becoming harder to avoid. Washington has grown more suspicious of Chinese economic activity across the board. That framing is met with skepticism in much of the region, but Beijing is no longer viewed as the white knight some governments once believed it to be. Amid increased pushback in the region, China is acting more assertively to protect its assets and market access.
Other notable shifts are adding their own pressures. As Beijing works to offload excess industrial capacity, China’s exports to the region have surged both in general and in comparison to its imports. According to Chinese Customs data, Latin American imports from China have outpaced its exports to China since 2021, resulting in a $46 billion trade deficit in 2025.
This trend is likely to continue. The 15th Five-Year Plan aims to enhance the quality and performance of China’s foreign trade and diversify into a wider range of markets—a redirection Latin America is already absorbing.
The region should expect more of all sorts of exports in the coming months, from high-end goods like EVs and industrial machinery to a substantial volume of low-cost goods moving through e-commerce channels. With Chinese firms locked in brutal domestic price wars, the search for buyers has been relentless, and even Latin America’s smallest markets are seeing the effects.
Squeezed from both sides
Latin American countries are taking different paths to deal with these pressures. Mexico is among those that have moved closer to Washington’s line: It has nearly doubled its filings of anti-dumping cases against Chinese goods, and it has floated tariffs on more than a thousand Chinese product lines, including autos, textiles, and steel.
Brazil has largely gone the other way, deepening ties with Beijing on soy, beef, and energy even as it absorbs tariff pressure from the U.S. And Chile has seemingly split the difference, maintaining duties on Chinese steel, footwear, and apparel while continuing to court Chinese investment in public works and renewables.
All of these paths carry costs. China is standing by its claims, launching counter-investigations, and warning governments against what it calls capitulation to Washington. The U.S. is also digging in its heels. In some countries, Washington’s posture has shifted from calibrated scrutiny of specific security risks—such as ports, telecommunications infrastructure, and critical minerals—to near-blanket suspicion of anything China-led.
The Trump administration is unlikely to change course. There is an apparent consensus in Washington that economic and military coercion is achieving desired effects in the region, regardless of the long-term costs of that approach.
In Latin America, even those governments seeking alignment with Washington have grown weary of its pressure tactics. Regional enthusiasm for closer ties to China has also cooled, whether due to unresolved debt obligations, diplomatic payoffs that haven’t materialized, or underwhelming returns from Chinese manufacturing investment.
Meanwhile, electorates across the region are watching closely to see how their leaders navigate the squeeze. For now, U.S. economic policy and military action are dominating the region’s attention. But China’s economic engagement—and the structural shifts likely to result from its shifting industrial strategy—will continue to have significant effects that should not be overlooked.
ABOUT THE AUTHOR
Margaret Myers
Reading Time: 3 minutes
Myers is a faculty lecturer at the Johns Hopkins School of Advanced International Studies, a senior advisor to the Inter-American Dialogue, and an adjunct researcher at the Núcleo Milenio sobre los Impactos de China en América Latina (ICLAC) in Chile
China’s New Playbook for Latin America
Beijing is shifting from an era of large loans and infrastructure initiatives toward more targeted, strategic engagement.
China’s Green-Tech Push in Latin America Is Gaining Traction
A surge of investment in the region is set to intensify, even as the hemisphere turns rightward.